

Nationwide SmartRide® analysis by Appwee
I look at Nationwide SmartRide® as a decision tool for drivers who want to explore whether their everyday driving could support a lower auto-insurance cost. It is a free app from Nationwide in the Auto & Vehicles category, and its purpose is much narrower than a general driving assistant: it connects driving behavior with Nationwide’s SmartRide program rather than trying to replace navigation, vehicle maintenance software, or a full insurance-management app.
That focus is both its appeal and its main limitation. If I were already considering Nationwide and wanted a way to participate in its usage-based insurance offering, I would take this app seriously. If I simply wanted trip planning, roadside help, fuel tracking, or a broad dashboard for my car, I would look elsewhere. The important question is not whether the app has the biggest feature list; it is whether its driving-based insurance approach makes sense for your situation.
How I would decide whether SmartRide fits
My first decision criterion would be the insurance relationship. SmartRide® is made by Nationwide, so the app is most relevant to someone who is a Nationwide customer or is actively evaluating Nationwide auto insurance. It is not a general-purpose telematics tool that I would install just to collect driving statistics for personal curiosity. The value comes from using the program as part of an insurance decision.
The second criterion is comfort with behavior-based pricing. An app like this asks me to accept that driving information can play a role in an insurance program. That can be attractive when I drive carefully and consistently, but it may feel less appealing if I prefer a traditional policy structure with less emphasis on app-based monitoring. I would make that choice before judging the interface, because no polished screen can remove that basic trade-off.
The third criterion is how predictable my driving is. Someone who mainly drives calmly on familiar roads may find a usage-based program easier to evaluate than someone whose driving changes dramatically from week to week. A commuter, a parent sharing a car, and a person who drives for work may each experience the program differently. The app is therefore not something I would assess only from its download page; I would think about who actually uses the vehicle.
I would also consider phone habits. A driving app needs to fit into the background of a normal trip without becoming another task I must remember to manage. Before relying on it, I would check the app’s setup instructions, review the permissions it requests, and make sure my phone is configured in a way that allows the intended experience. I would not start a journey by manually interacting with the screen, since safe driving has to come first.
There is a useful distinction here between an insurance app and a driving companion. A driving companion is usually judged by maps, alerts, maintenance records, or trip history. SmartRide is judged by whether its participation process is understandable, whether it fits my driving routine, and whether the potential insurance benefit justifies sharing driving-related information. That is the right lens for reviewing it.
What the app is trying to measure in practical terms
The app’s role is to support Nationwide SmartRide, a program built around driving behavior. In everyday use, I would think of it as a record of how I drive rather than a coach that turns every trip into a lesson. That difference matters. I would not install it expecting detailed mechanical diagnostics or a replacement for a vehicle’s dashboard.
A realistic scenario would be a driver who leaves home for work, makes a school drop-off, and runs an errand on the way back. With SmartRide in the background, the driver can follow the normal routine instead of creating artificial test drives. The useful result is a picture of ordinary driving, not a single unusually careful trip prepared for the app. That is one of the most important practical tips I would give: use the vehicle normally and judge the program over a representative routine.
I would also avoid treating one awkward journey as the whole story. Traffic, road design, weather, and an unexpected detour can make a trip feel unlike the rest of the week. A fair decision should come from understanding the program’s overall participation process and looking at normal patterns, rather than reacting to one frustrating drive.
Another non-obvious point is that the person installing the app may not be the only person whose driving matters. In a household with shared vehicles, I would clarify which driver and vehicle the program is intended to cover before assuming the results will reflect my own habits alone. That small check can prevent a confusing experience later, especially when several people use the same phone, car, or insurance policy.
What stood out in my day-to-day evaluation
The strongest part of SmartRide is its direct connection between an app and a concrete insurance purpose. I do not have to invent a reason to open it. The reason is clear: participate in Nationwide’s SmartRide offering and see whether that approach belongs in my insurance planning. That clarity makes it easier to recommend than a vague driving tracker whose information never leads to a practical decision.
I also appreciate that the app is free to download. That removes an initial payment barrier, although free installation should not be confused with a guaranteed insurance outcome. The real cost is the time spent enrolling, understanding the program, and deciding whether the privacy and monitoring trade-off feels worthwhile. I would read the participation details carefully instead of assuming that downloading alone changes my policy.
The public response is encouraging without being a substitute for personal fit. SmartRide has an average rating of 4.4 from around 1.2 thousand ratings, and it has passed 100 thousand installs. Those figures suggest that many people find the concept usable, but they do not tell me whether it will suit a driver with my schedule, household setup, or expectations. I treat them as a sign to investigate, not as proof that every experience will be smooth.
Nationwide is the developer, which gives the app a clear identity rather than making it feel like an unrelated add-on. I would still separate trust in the insurer from trust in the interface. A familiar company can make enrollment feel more comfortable, but I would judge the app itself by how clearly it explains what I need to do and how easily it fits into my routine.
The age rating is Everyone, which makes the app broadly approachable from a content standpoint. That does not mean every family should hand a young driver the phone and let the app decide what is best. Insurance decisions belong with the policyholder, and any household using shared vehicles should discuss who is participating and why.
Small workflow choices that make a difference
I would begin setup at home, not in a parking lot just before leaving. That gives me time to sign in, understand the screens, and check the phone settings without rushing. It also reduces the temptation to troubleshoot while driving. For an app tied to driving behavior, a calm setup is more important than quickly reaching the first trip.
I would keep the phone in a stable, sensible location and avoid changing settings during a journey. Even if the app is designed to work with limited interaction, the safest workflow is to prepare before moving. If a trip does not appear as expected, I would wait until I am parked before investigating rather than trying to correct it on the road.
I would also compare the app’s record with my own calendar during the first few days. Not to challenge every trip, but to learn whether the routine is being represented as I expect. This is a useful diagnostic habit for any driving-monitoring program: first establish that the setup matches the intended vehicle and driver, then decide whether the broader insurance trade-off is acceptable.
Finally, I would not use a short period of unusually cautious driving as my only basis for choosing a policy. The better question is whether my normal habits are compatible with the program. If I must constantly alter ordinary travel to feel comfortable, the potential benefit may not justify the mental effort.
Where alternatives may fit better
SmartRide is not automatically the best option simply because it is free. A traditional insurance policy may suit someone who values predictability and does not want driving behavior connected to an app-based program. In that case, the alternative is not another app; it is a different insurance structure. I would compare the overall policy terms directly rather than assuming a usage-based option is always cheaper.
A competing insurer’s telematics program may be a better fit for a driver who is already happy with that insurer or whose existing policy offers a clearer enrollment path. I would compare how each company explains participation, what information it asks for, and how comfortable I feel with the account relationship. Without reliable, current details about another company’s program, I would avoid choosing based on a headline promise alone.
For people who mainly want trip records, navigation, or vehicle reminders, a dedicated driving or navigation app is more appropriate. Those tools are designed around journeys and car ownership rather than insurance participation. SmartRide can coexist conceptually with them, but it does not replace their main purpose. Installing it for maintenance tracking would be a category mistake.
There is also a case for skipping telematics altogether. I would choose that route if the driver rarely uses a smartphone during travel, shares a car in a complicated way, has inconsistent access to the participating vehicle, or simply dislikes the idea of behavior-based insurance. The app may be perfectly functional and still be the wrong personal choice. Convenience and privacy preferences matter as much as the potential saving.
One trade-off that deserves more attention is the difference between a possible benefit and a guaranteed benefit. SmartRide’s store summary presents it as a way to save on auto insurance, but I would not interpret that as a promise that every driver will receive the same result. Before switching insurers or changing a policy, I would review Nationwide’s current program terms and ask the insurer how participation affects my particular situation.
I would also ask whether the app’s intended use matches my household. A single driver with one regularly used car has a simpler decision than a family with several vehicles and rotating drivers. If the app cannot be integrated cleanly into the way the household actually drives, a conventional arrangement may be less frustrating even if it lacks the appeal of tracking-based savings.
The real cost of switching to a monitored approach
The download itself costs nothing, but switching to SmartRide involves more than pressing an install button. I would spend time reading the enrollment steps, checking the correct account, preparing the phone, and learning how the program fits with my policy. That is a modest commitment, yet it is still a commitment. People who want an instant discount with no setup should lower their expectations.
There is a privacy cost as well. I would want to understand what driving-related information is used within the program, how it relates to my insurance account, and where to find the applicable terms. I would not rely on assumptions based on other tracking apps, because insurance programs can have their own rules. This is a situation where a few minutes of careful reading can prevent an unpleasant surprise.
There can be a social cost in a shared car. If one person drives carefully but another person uses the vehicle regularly, the household needs a common understanding of participation. I would discuss the arrangement before enrolling, especially when the car is used for work, school, or long trips by several people. That conversation is easy to overlook and can matter more than the app’s visual design.
Technical friction is another possible cost. Phones differ in battery management, background activity settings, and operating-system behavior. SmartRide requires a minimum operating system of 10, so I would check compatibility before planning around it. The current version is identified as nwsmart-v4.4.0.0-98115-g88ef6c5-prod, which tells me the app is actively versioned, but I would still keep the phone and app maintained rather than assuming an old setup will behave perfectly.
If I changed phones, vehicles, or insurance arrangements, I would revisit the setup instead of assuming the old configuration carries over cleanly. That is a practical switching cost many people discover only after a change. Keeping account details and vehicle information organized makes the transition easier and gives me a clearer basis for contacting Nationwide if something does not line up.
Who I would recommend it to
I would recommend SmartRide to a Nationwide customer who is comfortable with usage-based insurance, drives a fairly representative routine, and is willing to read the program terms before enrolling. It is especially sensible for someone who wants to investigate a potential insurance saving through normal driving rather than add another app for entertainment or convenience.
I would also point it toward a careful shopper comparing insurers. The app can be part of a broader decision, but I would compare the full policy, service experience, coverage needs, and participation requirements. A possible telematics benefit should not make me overlook a policy that is otherwise a poor match.
I would be more cautious recommending it to a driver who wants precise control over every piece of personal data, dislikes background tracking, or expects a detailed dashboard of vehicle health. Those expectations belong to other categories of products. SmartRide’s value is concentrated in the insurance-program connection, and that concentration should be understood before installation.
My final view is positive but conditional. Nationwide SmartRide® is a focused, free Auto & Vehicles app from Nationwide with a clear reason to exist: helping drivers participate in a behavior-based auto-insurance program. Its average rating of 4.4 and broad adoption give it a reasonable starting level of confidence, while the Everyone age rating keeps it accessible to a wide audience. Still, I would choose it for the insurance decision, not for general driving features.
My recommendation is to try it only after confirming that the SmartRide program matches your policy, your household’s driving pattern, and your comfort with monitoring. For the right Nationwide driver, it can be a practical way to explore savings through ordinary trips. For everyone else, a traditional policy or a purpose-built navigation and vehicle app may be the more honest fit.
Gallery
Nationwide SmartRide® Pros and Cons
- Real-time ride tracking helps you monitor your vehicle’s location.
- Digital trip history makes it easier to review recent journeys.
- Convenient access to SmartRide account and vehicle details.
- Can help identify driving patterns through recorded trip information.
- Useful for managing SmartRide services while away from your vehicle.
- Requires a compatible Nationwide SmartRide policy and enrolled vehicle.
- Location and driving data collection may concern privacy-conscious users.
- Some features depend on reliable GPS
- mobile data
- and background access.
- Battery usage may increase when tracking services run continuously.
- App usefulness is limited if you rarely drive or use Nationwide services.
Nationwide SmartRide® Frequently Asked Questions
What is Nationwide SmartRide® and how does it work?
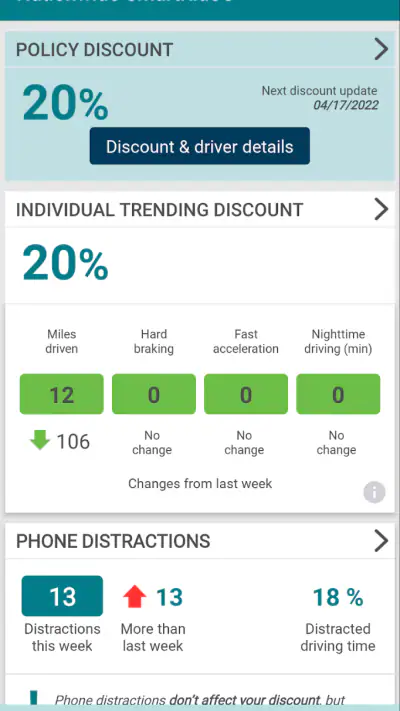
Nationwide SmartRide® is a usage-based insurance program that uses information about your driving habits to help determine whether you may qualify for a discount on your auto insurance. After enrollment, the app or connected tracking method records eligible driving data, such as mileage, braking, acceleration, time of day, and other driving patterns. Your results are presented through the app so you can monitor your progress and adjust your habits.
What information does Nationwide SmartRide® collect from my phone?
Depending on your enrollment method, Nationwide SmartRide® may collect driving-related information such as trip distance, speed, acceleration, braking, phone movement, and the time or location associated with a trip. The app may use your phone’s sensors, GPS, Bluetooth, and motion data to identify driving activity. Before enrolling, review the current permissions and privacy terms because requirements can vary by device, state, policy, and program version.
Can Nationwide SmartRide® lower my insurance premium?
The main purpose of Nationwide SmartRide® is to give eligible policyholders an opportunity to earn an auto insurance discount based on qualifying driving behavior. The exact discount, eligibility requirements, evaluation period, and effect on your policy can vary by state and insurance contract. A safe driving score does not guarantee a specific savings amount, so confirm the current terms with Nationwide or your insurance agent.
Does Nationwide SmartRide® affect my insurance if I drive poorly?
Nationwide SmartRide® is generally promoted as a discount opportunity rather than a program designed to increase your premium because of an unfavorable score, but the precise rules depend on your state and policy. Driving data can still be used according to the program’s terms, and incomplete participation may affect eligibility for a discount. Read the enrollment documents carefully before activating tracking.
What should I do if SmartRide® does not detect a trip correctly?
Trip detection can be affected by disabled location services, restricted background activity, low battery, weak GPS reception, Bluetooth problems, or the phone being left in an unusual position. Keep the app updated, allow the required permissions, and avoid force-closing it before driving. If a trip remains missing or is classified incorrectly, use the app’s support options or contact Nationwide promptly for assistance.














